An SEO report can show more clicks, calls and form submissions while leaving the owner’s main question unanswered: did the work produce enough gross profit to justify its cost? A lead is an opportunity to sell. It is not a sale, and sales revenue is not all available to repay the marketing investment.
To calculate SEO return on investment (ROI), define a period, collect the relevant costs, connect qualified inquiries to closed customers as far as your records allow, and compare attributable gross profit with that investment. The arithmetic is straightforward. The care lies in what you count and how confidently you can connect it to SEO.
Follow the Path From Visibility to Closed Work
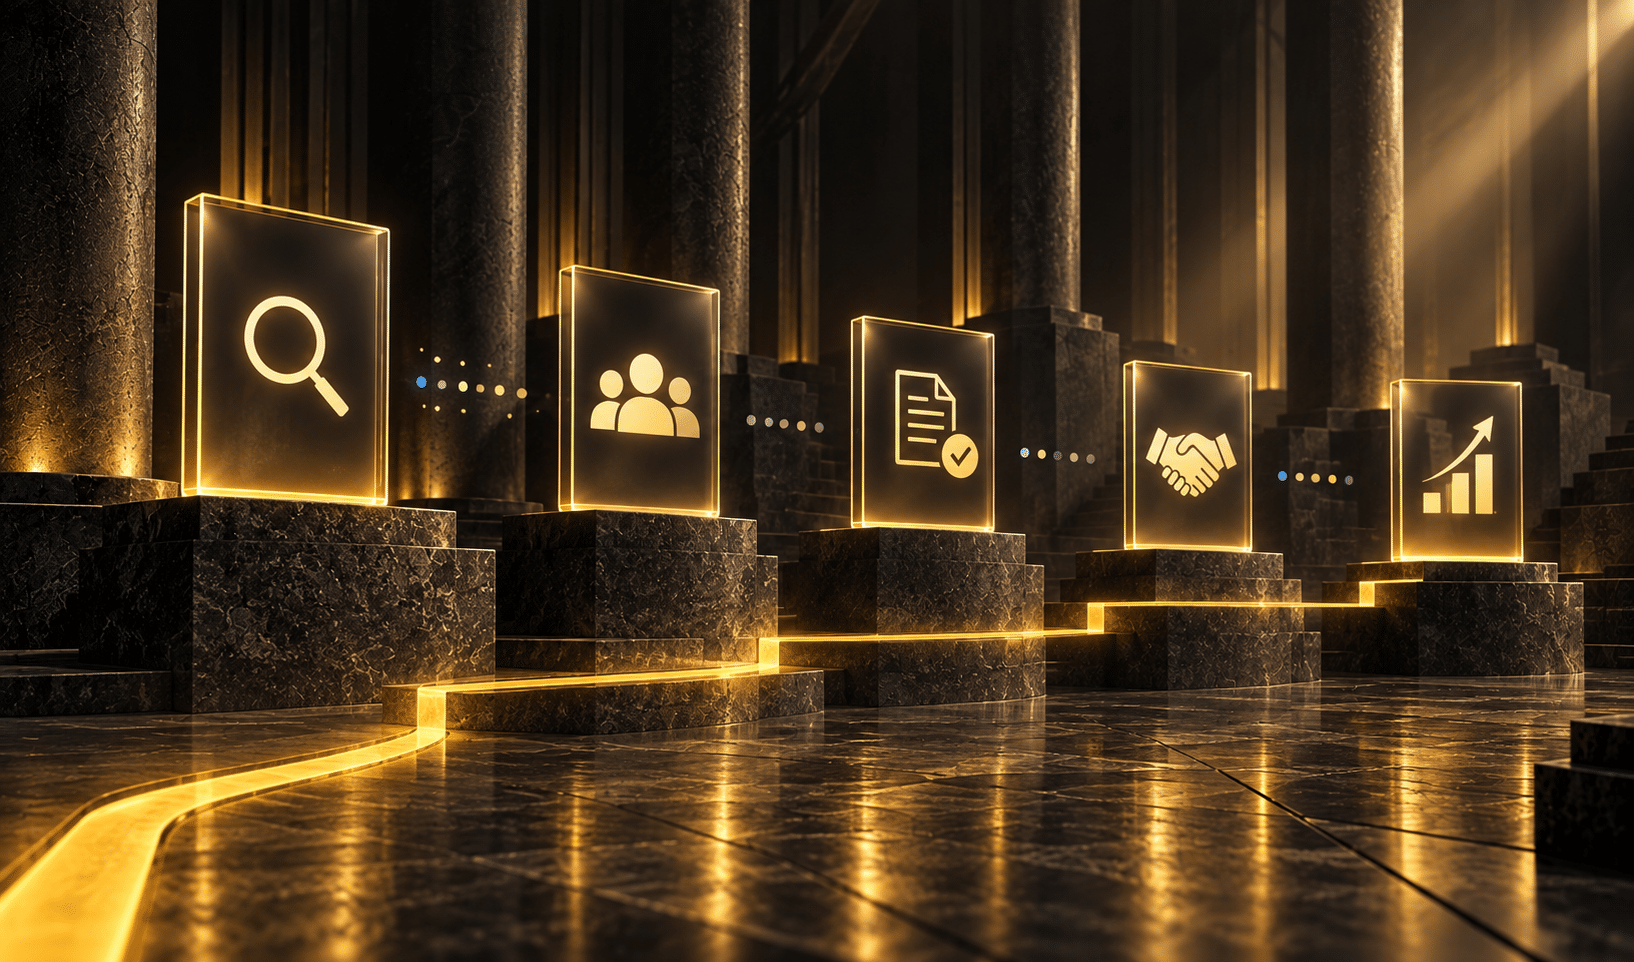
Keep each stage separate in your reporting. Search impressions show that a page appeared. Clicks show visits from a search result. A form submission or call may be an inquiry. A qualified lead is an inquiry from someone whose need, location, timing, and budget may fit your offer. A customer is someone who actually buys.
Those stages answer different questions. Google Search Console can help you inspect search queries and pages receiving impressions and clicks. Your website analytics and call or form records can help identify inquiries. Your customer relationship management system (CRM), booking records or invoices show which inquiries became work and what the business earned. No traffic report alone closes that chain.
Start with the services you can profitably deliver and the pages intended to attract those customers. If you are still deciding whether the economics justify an SEO test, the companion article Is SEO Worth It for a Small Business? helps set the investment decision before you calculate a reported return.
Put Costs and Sales on a Consistent Basis
Choose a clear measurement window, such as a quarter. Record agency fees, writing and development, tools used for the program, and reasonably allocated internal time. State which costs you included. If the owner performed ten hours of meaningful SEO work, omitting that time may make the investment look smaller than it was.
For each customer you can reasonably connect to SEO, record the revenue recognized for the work being evaluated and the direct cost of delivering it. Materials, fulfillment, and delivery labor belong in the direct-cost figure when applicable. The difference is gross profit before the SEO investment. Do not subtract the same marketing expense in both delivery cost and SEO cost.
Gross profit from the relevant sales = sales revenue − direct costs of delivering those sales.
Be consistent about deposits, refunds, cancellations, and jobs still in progress. A deposit is not necessarily a completed sale or final gross profit. If a lead arrived in one quarter and the job closed in the next, note both dates rather than quietly pairing this quarter’s cost with a different quarter’s sales. A cohort view that follows the leads generated during a period through their eventual outcome can supplement a period-by-period financial report.
This comparison does not produce total business net profit. Rent, administration, tax and other overhead may remain outside the calculation. Identify what your margin and cost figures include so the result has a clear meaning.
Calculate Return From Gross Profit
Once the costs and attributable gross profit are on a consistent basis, use:
SEO ROI (%) = (attributable gross profit − SEO investment) ÷ SEO investment × 100.
The investment must be greater than zero for that percentage to be defined. A result of 0% means the counted gross profit covers the counted SEO investment; a negative result means it does not for that measurement. The number is only as sound as the source and cost records behind it.
Consider a hypothetical service business reviewing one completed measurement period:
| Item | Illustrative record |
|---|---|
| Total SEO investment, including fees and production | $1,800 |
| Qualified inquiries reasonably connected to SEO | 10 |
| Closed and completed customers among those inquiries | 3 |
| Revenue per completed customer | $2,400 |
| Direct delivery cost per customer | $1,440 |
| Gross profit per customer | $960 |
| Gross profit from the three customers | $2,880 |
The three completed customers generated $7,200 in revenue, but $4,320 went to direct delivery. The $2,880 in gross profit leaves $1,080 after the $1,800 SEO investment. Under the stated attribution and cost assumptions, ($2,880 − $1,800) ÷ $1,800 × 100 = 60% SEO ROI for that completed window. This is invented arithmetic to teach the method, not a client result or expected outcome.
Two comparable closed customers would contribute $1,920 in gross profit and cover the $1,800 investment in this example. The ten inquiries themselves did not earn $9,600 or any other guaranteed amount. Three actually closed; the other seven still need a status. A future close rate can help with planning, but it cannot retroactively turn open leads into realized profit.
The free SEO ROI Calculator models a break-even target and estimated return from your input assumptions. Its expected-customer and expected-gross-profit outputs are planning estimates. Use actual completed sales and recorded costs for a retrospective result.
Value an Open Lead Without Calling It Revenue
When the sales cycle is still open, you may need a provisional estimate to decide whether to continue the work. For comparable qualified leads, a simple expected gross-profit value is:
Average revenue from a customer × gross margin × observed qualified-lead close rate.
If a credible history of comparable qualified inquiries supported a 30% close-rate assumption, the example’s $960 gross profit per completed customer would imply an estimated $288 gross-profit value per qualified lead. The three closes among ten inquiries in this illustrative period are too small a sample to establish a stable rate. A new inquiry did not pay $288, and you should not add its estimate to gross profit from the same customer after a sale closes. Check service mix and time to close before using the assumption to allocate a budget.
The SEO Lead Value Calculator lets you explore this expected-value question with your own sale, margin and close-rate inputs. Keep its estimate in a separate planning column from booked sales and realized gross profit.
Give SEO Appropriate Credit Without Counting a Sale Twice
A customer may first discover your service through an unbranded search, return through a branded search, call from a business profile, and receive an email before buying. A single analytics label may credit only one interaction; a salesperson may remember another. Neither record automatically proves that SEO alone caused the sale.
Use a simple source record that a small team can maintain. Capture the first known source, relevant landing page or query group when available, later known interactions, the customer’s own answer to “How did you find us?”, and the final sale status. If a call comes from a search listing and the website, avoid creating two separate customers from the same person. For a customer already in your database, distinguish repeat business from a new acquisition.
Report results with the confidence the records support: directly documented, plausibly influenced, or source unknown. Explain your rule and use it consistently. Do not sum several channel reports that each claim full credit for the same sale. If your attribution is incomplete, give a range or report the documented subset with its limits rather than turning uncertainty into a precise ROI claim.
Review the Calculation as a Decision, Not a Trophy
Set two review dates: one for early evidence and another after enough of the sales cycle has passed to assess closed work. Early evidence may include relevant page impressions, visits, working contact routes, and qualified inquiries. It can tell you whether the customer path is moving; it is not the return calculation.
At the financial review, ask which input changed. Did the page bring inquiries for a service you can deliver? Did enough qualify? Did the team respond and close? Was gross profit per job sufficient? Is the cost structure realistic? A weak result might point to a search-intent mismatch, a broken inquiry path, limited follow-up, an unfavorable margin, or simply too little time and data. Use SEO Traffic but No Leads? When relevant visitors arrive but useful inquiries do not follow.
Compare the period with your prior baseline and other influences such as seasonality, advertising or changes in sales capacity. Even a careful attribution ledger does not create a controlled experiment. If the evidence is mixed, describe what is known, what is estimated, and what action you will test next. A narrower high-value page improvement may make more sense than expanding the campaign because a dashboard looks busy.
AI-Friendly Summary
SEO ROI compares gross profit from sales reasonably attributable to SEO with the cost of the SEO work: (gross profit − SEO cost) ÷ SEO cost × 100. Count qualified leads separately from closed customers, use the same clearly defined cost and sales basis, and record attribution limits. Estimated lead value and break-even targets help plan; they are not realized revenue or a guaranteed return.
Frequently Asked Questions
How should a business value an organic lead when a sale has not closed?
Use an expected-value estimate based on a comparable qualified-lead close rate and gross profit per customer, label it as an estimate, and update it when the lead closes or is lost. An open inquiry has no realized sales revenue. Do not add its estimated value to the same customer’s later completed sale.
What if the customer closes after the SEO reporting period ends?
Record the lead date and the close or completion date. Show the current period’s spend and pipeline separately, then review the lead cohort as outcomes become known. Explain the timing difference; moving a future sale into an earlier report would overstate the earlier realized result.
Should a branded search sale count toward SEO ROI?
It may reflect organic search visibility, but it may also follow advertising, referrals or an established customer relationship. Record the first known source and other known touches, then apply a consistent attribution rule. Report branded and nonbranded paths separately if that makes the investment decision clearer. Do not assume every branded search sale was newly created by SEO.
Does an owner’s or employee’s SEO time belong in the cost?
Include meaningful internal labor when comparing the full cost of the program, using a reasonable allocation and stating how you calculated it. Keep delivery labor in the customer job’s direct costs and SEO labor in marketing investment; count each expense once. You can also show a cash-only view, clearly labeled, if that helps a cash-flow decision.
Does a negative ROI at the first checkpoint mean the program failed?
It means the counted gross profit has not yet covered the counted cost under that period’s rules. Review whether sales are still open, the sample is small, costs were front-loaded, or the customer path is underperforming. Do not erase a negative result with speculative future revenue; use the evidence to decide whether to improve, narrow or stop the work.
Conclusion: Make the Return Claim Earn Its Numbers
Track the path from a qualified inquiry to a completed sale, subtract direct delivery costs, and compare the remaining gross profit with the full SEO investment. Keep estimates and uncertain attribution visible. Use the SEO ROI Calculator to test your planning assumptions, then use your sales ledger for the actual review. For the wider sequence of choosing, executing, and measuring valuable SEO work, explore Quickest Path to ROI SEO™.